
Quick Summary: March 2026 Sees $82 Billion Asset Dump Amid Iran Conflict
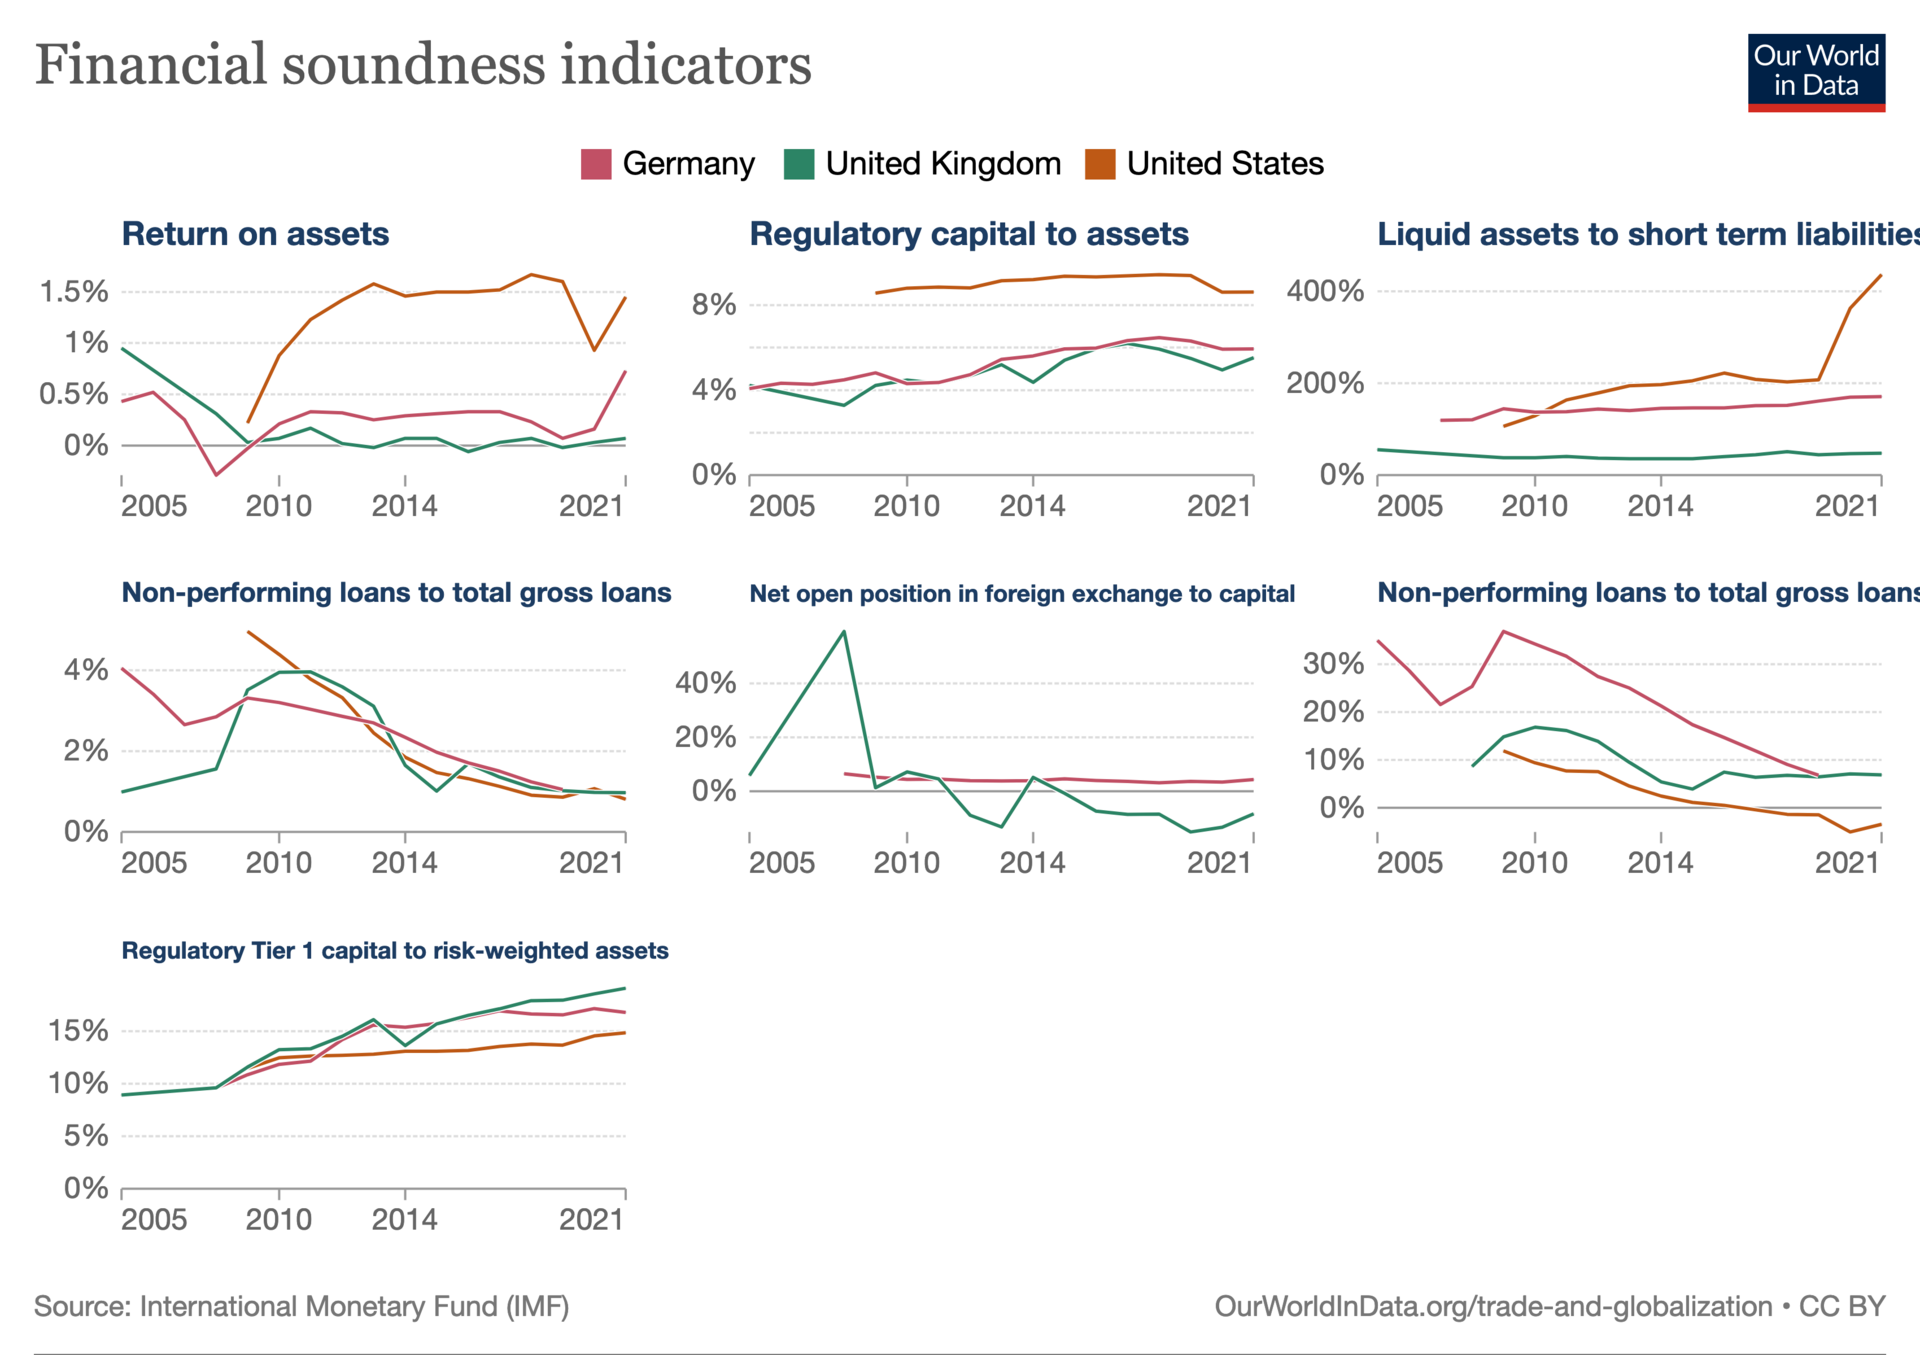
- Emerging markets are experiencing smaller capital-flight shocks due to stronger central banks and lower public debt, according to OECD analysis.
- A March 2026 stress episode saw $82 billion in emerging-market portfolio assets dumped, highlighting ongoing global shock volatility.
- Panel evidence from 23 emerging markets shows global drivers still affect inflows but less severely than in the pre-2008 crisis period.
- Central bank independence and fiscal discipline are identified as key buffers against global financial turbulence.
- Geopolitical risk has become a significant factor affecting portfolio inflows and foreign direct investment.
Source: Open external resource
Source: Read original article
In a world where financial storms are as unpredictable as the weather, emerging markets have found a way to brace themselves against the worst of it. The latest OECD-backed analysis reveals that these markets are no longer uniformly vulnerable to global financial shocks. Instead, countries with robust central banks and low public debt are experiencing fewer capital-flight shocks even amidst global turmoil. March 2026 is at the center of this development.
The analysis, published by CEPR’s VoxEU, spotlights a March 2026 event where $82 billion in emerging-market assets were offloaded, marking the severity of ongoing global financial volatility. Yet, the core argument is that the impact of such shocks has diminished since the 2008-09 crisis. This change is attributed to policy improvements, particularly in central bank independence and fiscal discipline, which have fortified these economies against external financial turbulence.
What stands out in this analysis is the new role of geopolitical risk. Once a background concern, it now significantly affects both short-term portfolio inflows and long-term foreign direct investment. This shift underscores the complex dynamics of global finance, where country-specific risks can ripple through markets, affecting investment decisions far beyond immediate market nerves.
While the debate on macroprudential policy continues, the findings challenge the notion that such measures alone can shield emerging markets from financial turmoil. As non-bank financial institutions increasingly mediate international flows, traditional defenses may require rethinking to address these evolving challenges effectively.
As the global financial landscape evolves, emerging markets must adapt their strategies to protect against future shocks. The focus on central bank independence and fiscal discipline offers a blueprint for resilience, but the growing influence of geopolitical risk calls for a nuanced approach to policy design. The next steps involve regulatory discussions on extending macroprudential thinking beyond traditional banking systems to prepare for the next financial upheaval.
They anchor their argument in an OECD 2024 report on capital-flow resilience and connect it to recent stress events including the 2022-2023 Federal Reserve tightening cycle and the March 2026 Iran-war shock. The most concrete new data point in the piece is a March 2026 stress episode tied to the war in Iran, when foreign investors dumped $82 billion of emerging-market portfolio assets in a single month, which the authors call “a record in recent years” based on OECD data.
Using panel evidence covering 23 emerging markets from 2010 through 2023, the authors say global drivers such as risk aversion, uncertainty, US dollar strength, commodity-price declines, and geopolitical risk still push portfolio inflows lower, but not as brutally as they once did. That figure is the article’s clearest sign that global shocks are still violent, but the reporting’s central claim is that the transmission of those shocks has weakened since the 2008-09 global crisis.
According to the authors, fund-level evidence shows international equity and bond funds actively cut exposure to countries facing elevated geopolitical risk, and bond investors are even more sensitive than equity investors. What happens next, according to the logic of the reporting, is not a legislative vote or court deadline but a regulatory and policy fight over how to protect emerging markets from non-bank-driven capital swings.
The column was published by CEPR’s VoxEU on September 22, 2026, and written by OECD economists Annamaria de Crescenzio, an economist and manager in the OECD’s International Finance Unit, and Etienne Lepers, a fellow economist in the same unit. Their empirical split between pre-crisis years, 2000-2007, and post-crisis years, 2010-2023, is the backbone of the story: estimated sensitivities of both equity and debt inflows to global shocks were “materially smaller” in the later period.
The CEPR column was published today, September 22, 2026; it points back to the March 2026 $82 billion outflow episode as the freshest real-world stress test; and it says geopolitical effects have become notably stronger since February 2022. ” A second important development in the latest reporting is the elevation of geopolitical risk from background noise to a distinct capital-flow driver.
That figure is the article’s clearest sign that global shocks are still violent, but the reporting’s central claim is that the transmission of those shocks has weakened since the 2008-09 global crisis. According to the authors, fund-level evidence shows international equity and bond funds actively cut exposure to countries facing elevated geopolitical risk, and bond investors are even more sensitive than equity investors.
What happens next, according to the logic of the reporting, is not a legislative vote or court deadline but a regulatory and policy fight over how to protect emerging markets from non-bank-driven capital swings. The column was published by CEPR’s VoxEU on September 22, 2026, and written by OECD economists Annamaria de Crescenzio, an economist and manager in the OECD’s International Finance Unit, and Etienne Lepers, a fellow economist in the same unit.
Their empirical split between pre-crisis years, 2000-2007, and post-crisis years, 2010-2023, is the backbone of the story: estimated sensitivities of both equity and debt inflows to global shocks were “materially smaller” in the later period. The CEPR column was published today, September 22, 2026; it points back to the March 2026 $82 billion outflow episode as the freshest real-world stress test; and it says geopolitical effects have become notably stronger since February 2022.
The scale and speed of this development has caught many observers off guard. Each new update adds another dimension to a story that is still unfolding, and the full picture will only become clear as more verified details emerge from the people and institutions directly involved.
Analysts who have tracked this issue closely say the current moment represents a genuine turning point. The decisions made in the coming weeks are expected to set the direction for months ahead, with ripple effects likely to extend well beyond the immediate actors in the story.
For those directly affected, the practical impact is already visible. People navigating this fast-changing situation are dealing with real consequences while new information continues to reshape what is known and what remains open to interpretation.
Historical parallels offer some context, though experts caution against drawing too close a comparison. Similar situations have played out before, but the specific combination of pressures, personalities, and timing here makes this moment distinct in ways that matter for how it ultimately resolves.
The political and economic dimensions of this story are deeply intertwined. What appears as a single event on the surface is in practice the convergence of multiple pressures that have been building quietly over a longer period than most public reporting has captured.