
Quick Summary: RBI’s 25 Basis Point Rate Hike Signals End to Easing Cycle
- Governor Sanjay Malhotra’s MPC raised the repo rate by 25 basis points to 5.50% — signaling a shift to ‘calibrated tightening’ and ruling out near-term rate cuts.
- Economists anticipated the 25 bps increase — marking the first hike since February 2023, affecting loans and market expectations.
- Inflation risks have broadened, driven by rising crude prices and a weakening rupee — prompting the RBI to act despite potential impacts on borrowers.
- The Standing Deposit Facility rate was adjusted to 5.25% — tightening the operating corridor around short-term rates.
- The RBI’s shift from ‘neutral’ to ‘calibrated tightening’ marks a clear departure from last year’s easing cycle — emphasizing inflation control as a priority.
Source: Open external resource
Source: Read original article
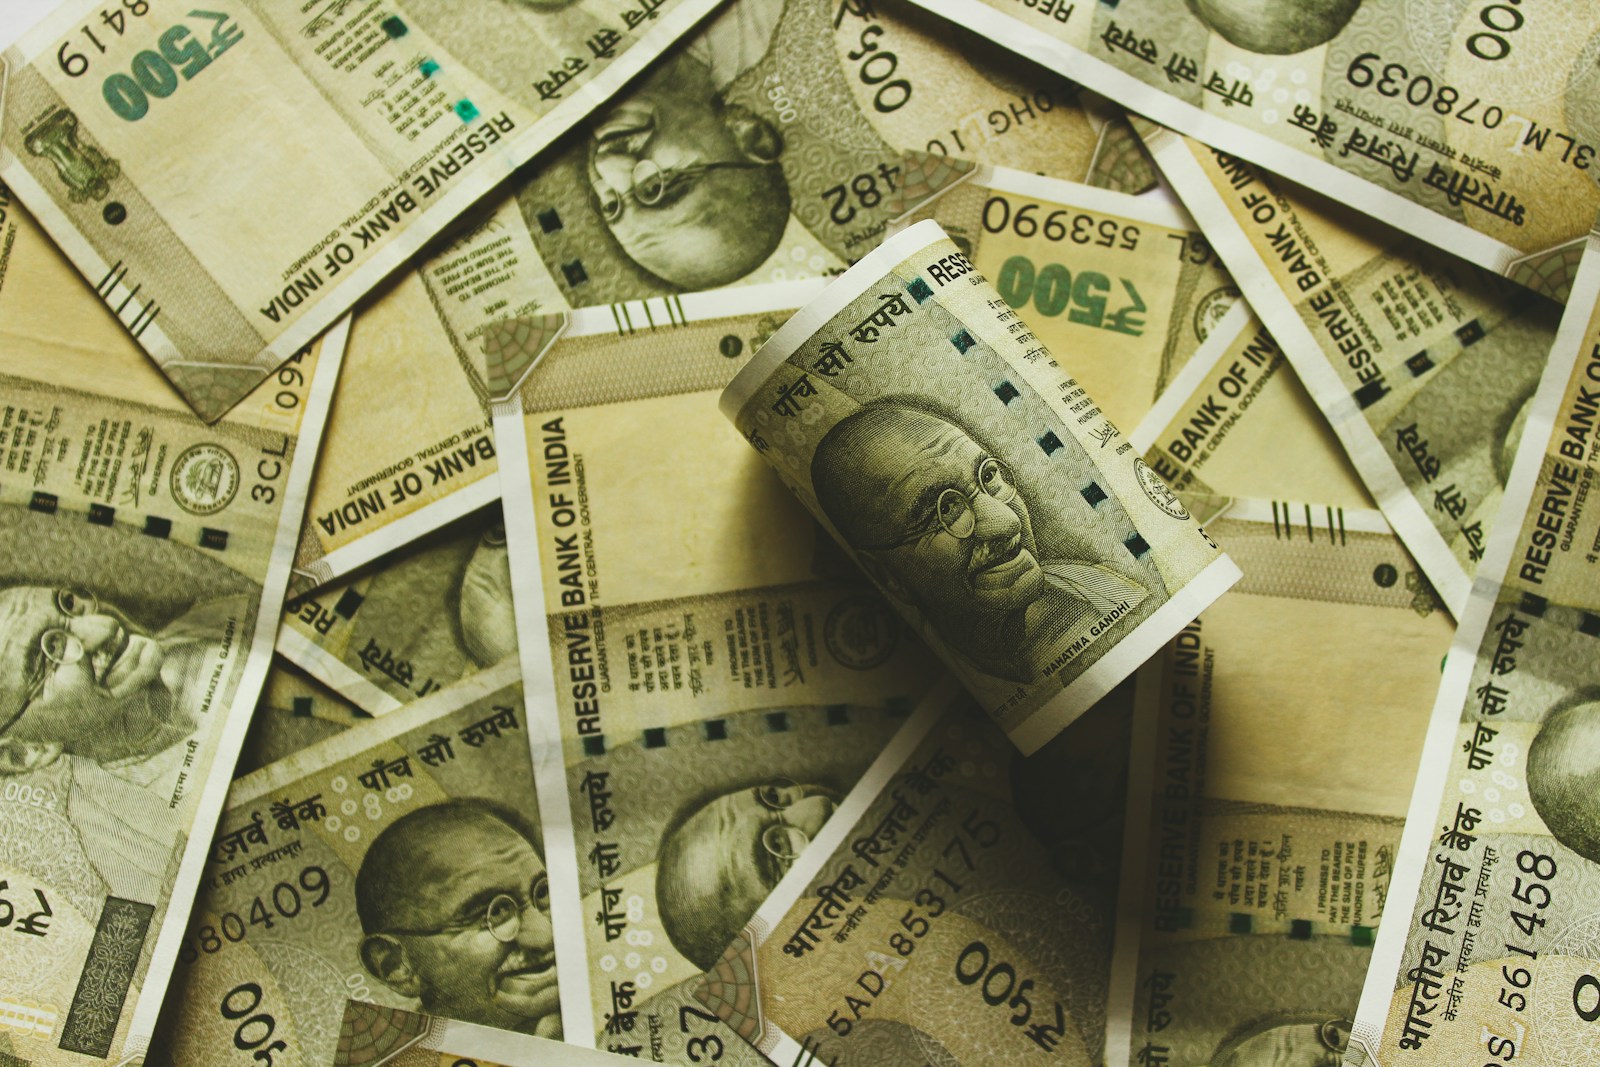
In a decisive move that reverberated through India’s financial landscape, the Reserve Bank of India’s Monetary Policy Committee, led by Governor Sanjay Malhotra, announced a 25 basis point hike in the repo rate to 5.50%. This decision, made on October 7, signals a significant pivot towards ‘calibrated tightening’, effectively putting any hopes of near-term rate cuts to rest.
The anticipation of this hike was palpable, with economists predicting the move as the first increase since February 2023. The decision is a direct response to escalating inflation risks, exacerbated by rising crude prices and a weakening rupee, which have left the RBI with little choice but to act decisively, despite the potential strain on borrowers and rate-sensitive sectors.
By adjusting the Standing Deposit Facility rate to 5.25%, the RBI has tightened the operating corridor around short-term rates, further underscoring its commitment to reining in inflation. This shift from a ‘neutral’ stance to ‘calibrated tightening’ is a stark departure from the easing cycle of the previous year, marking a renewed focus on inflation control as a top priority.
For Indian households, the implications are immediate and tangible. Floating-rate home loans, auto loans, and personal loans are set to become costlier, while savers might finally see improved fixed-deposit returns. The financial markets, now on edge, will closely scrutinize future RBI communications for any hints of further policy adjustments.
As the dust settles, the only question that remains is whether inflationary pressures will compel the RBI to act again. With Malhotra’s clear stance that the next move can only be a ‘hike or pause’, the debate has narrowed sharply, leaving the financial markets to brace for what comes next.
In the run-up to the decision, Business Standard reported economists expected a 25 bps increase and noted this would be the first repo-rate hike since February 2023. 5% in October and November before easing in early 2027, which helps explain why the committee moved despite the obvious hit to borrowers and rate-sensitive sectors.
25% alongside the repo increase, tightening the operating corridor around short-term rates. 25% through four policy reviews following a cumulative 125-basis-point reduction in 2025, so Wednesday’s move marks a clear reversal from last year’s easing cycle.
50% and the RBI’s stance hardened beyond a one-off move. The central conflict in this story is now clear: the RBI is choosing to lean harder against inflation even at the risk of making credit costlier and growth more fragile.
” That framing matters more than the 25-basis-point move alone, because it tells borrowers and traders the debate has shifted from whether easing might resume to whether inflation risks are severe enough to force another hike. The people and institutions at the center are Governor Sanjay Malhotra, the six-member RBI Monetary Policy Committee, and the financial markets that had been parsing every signal of intent.
On October 5 and 6, Moneycontrol and Mint previewed a decision day dominated by questions over the repo rate, inflation forecasts and Malhotra’s forward guidance. The practical takeaway from the latest reporting is that Indian households with floating-rate debt should expect pressure on EMIs or loan tenure, savers may finally see better FD rates, and traders will focus on whether “calibrated tightening” proves to be a one-meeting warning or the start of another hiking phase.
In the run-up to the decision, Business Standard reported economists expected a 25 bps increase and noted this would be the first repo-rate hike since February 2023. 50% — signaling a shift to ‘calibrated tightening’ and ruling out near-term rate cuts.
Economists anticipated the 25 bps increase — marking the first hike since February 2023, affecting loans and market expectations. The anticipation of this hike was palpable, with economists predicting the move as the first increase since February 2023.
25%, the RBI has tightened the operating corridor around short-term rates, further underscoring its commitment to reining in inflation. 5% in October and November before easing in early 2027, which helps explain why the committee moved despite the obvious hit to borrowers and rate-sensitive sectors.
25% — tightening the operating corridor around short-term rates. 50% and the RBI’s stance hardened beyond a one-off move.
The scale and speed of this development has caught many observers off guard. Each new update adds another dimension to a story that is still unfolding, and the full picture will only become clear as more verified details emerge from the people and institutions directly involved.
Analysts who have tracked this issue closely say the current moment represents a genuine turning point. The decisions made in the coming weeks are expected to set the direction for months ahead, with ripple effects likely to extend well beyond the immediate actors in the story.
For those directly affected, the practical impact is already visible. People navigating this fast-changing situation are dealing with real consequences while new information continues to reshape what is known and what remains open to interpretation.
Historical parallels offer some context, though experts caution against drawing too close a comparison. Similar situations have played out before, but the specific combination of pressures, personalities, and timing here makes this moment distinct in ways that matter for how it ultimately resolves.
The political and economic dimensions of this story are deeply intertwined. What appears as a single event on the surface is in practice the convergence of multiple pressures that have been building quietly over a longer period than most public reporting has captured.